Two houses in Berks County can look almost identical and still come with very different homeowners insurance quotes. A brick twin in Reading, a newer colonial in Wyomissing, and a farmhouse outside Oley might all be similar in size, but insurers see them through a completely different lens.
If you’ve ever compared quotes with a neighbor or a friend across the county and wondered why the numbers don’t line up, here’s what’s going on behind the scenes.
Your distance from fire protection
This is one of the biggest factors, and one most homeowners never think about. Insurers look at how close your home is to a fire hydrant and a responding fire station. Many carriers use a fire protection rating assigned to your area to help set prices.
In Reading and the surrounding boroughs, hydrants are usually close by and fire companies are minutes away. Out in the more rural townships, homes may rely on volunteer fire companies covering wide areas, with no hydrant nearby at all. Firefighters may need to bring water in by tanker. That added risk can push premiums higher.
The age of the home
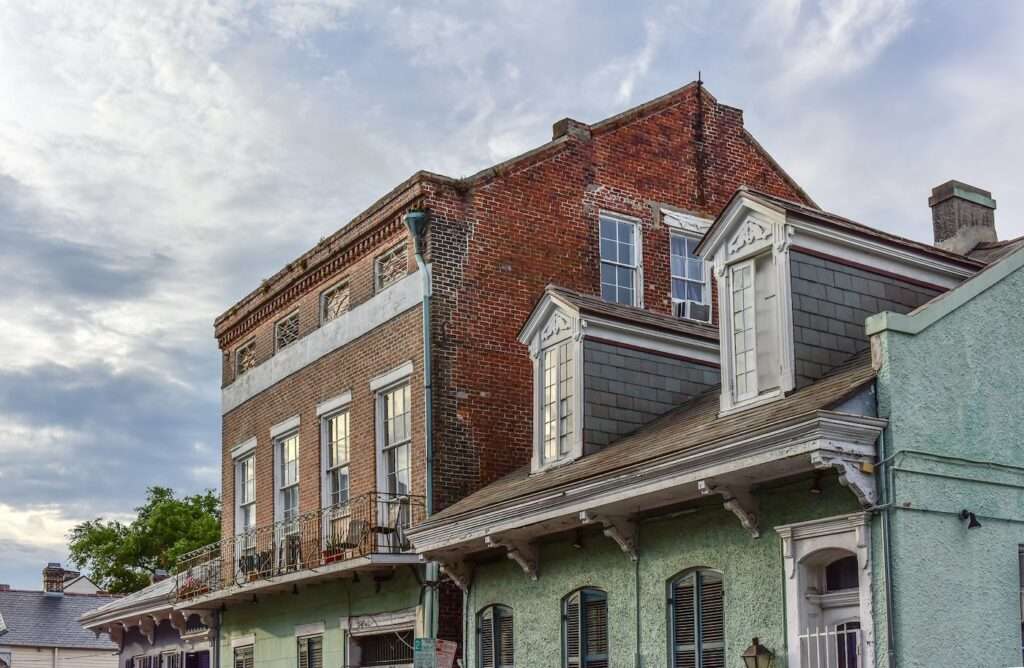
Berks County has a lot of older housing stock, especially in Reading, West Reading, and the county’s historic boroughs. Older homes have character, but they can also come with:
- Older electrical systems
- Aging plumbing
- Roofs that may be near the end of their life
- Materials and craftsmanship that cost more to replace
Insurers price for what it would cost to rebuild your home, not what you paid for it. A home with plaster walls, original woodwork, or stone construction can cost more to restore after a loss. If you’ve updated your roof, wiring, or plumbing, make sure your agent knows. Those upgrades can make a real difference.
Rebuild cost vs. market value
This trips up a lot of people. Your home’s market value includes the land and the neighborhood. Your coverage is based on replacement cost, meaning what it would take to rebuild the structure with similar materials.
That’s why a modest home in an affordable area can still carry a higher premium than expected. Construction and labor costs don’t change much from one Berks County zip code to the next, even when home prices do.
Water & weather exposure
Berks County is crisscrossed by the Schuylkill River and creeks like the Tulpehocken, Maiden Creek, and Manatawny. Homes near these waterways can face higher risk of water damage and flooding.
One important note: standard homeowners policies don’t cover flood damage. If you live near water, flood coverage is a separate policy, and it’s worth a conversation even if you’re not in a mapped flood zone.
Wind, hail, and winter storms also play a role. Heavy snow loads, ice dams, and frozen pipes are common claims in our area, and insurers factor in how often they see these claims locally.
Local claims history
Insurers track claims by area. If a neighborhood has seen a higher number of theft, water, or storm claims, premiums in that area may reflect it, even if you’ve never filed a claim yourself.
Your personal factors
Location matters, but so do the details specific to you:
- Your claims history
- Your credit-based insurance score (where permitted)
- Your deductible
- Security systems, smoke detectors, and water leak sensors
- Whether you bundle your home and auto policies
These are the levers you control and they can offset some of the location-based factors.
How these factors play out Across Berks County
| Factor | City and Boroughs (Reading, West Reading, Kutztown) | Suburban Areas (Wyomissing, Sinking Spring, Exeter) | Rural Townships (Oley, Bernville, Bethel) |
| Fire protection | Hydrants and stations close by | Generally good coverage | Often farther from hydrants and stations |
| Home age | Many older homes | Mix of older and newer construction | Mix, including older farmhouses |
| Rebuild cost | Can be higher for historic materials | Typically standard construction costs | Can be higher for stone or older builds |
| Water exposure | Varies by proximity to river and creeks | Varies | Varies, with some creek-adjacent properties |
| What to ask your agent | Credit for updated wiring, roof, plumbing | Bundling and deductible options | Fire protection rating and flood coverage |
Why shopping with an independent agent helps
Every insurance company weighs these factors differently. One carrier might be tough on older homes but competitive for rural properties. Another might do the opposite. That’s why your neighbor’s great rate doesn’t always translate to yours.
As an independent agency, The Kind Insurance works with multiple carriers, so we can compare options side by side and find the one that fits your home and your budget. No guesswork, no one-size-fits-all quote.
Want to see how your home stacks up? Reach out to The Kind Insurance for a free quote and a straightforward look at your coverage.